
Choosing in-network providers is one of the easiest ways to find quality care, save money, and make the most of your health plan. Let’s take a closer look at how to find in-network providers, what in-network means, and how staying in-network helps you manage your healthcare costs.
How to Find an In-Network Provider
Finding in-network doctors, specialists, and hospitals is simple when you use JoinHealth. Here’s how:
- From the home page, select the Find a Provider link
- If needed, enter the first three letters of your Member ID and your location
- Search for providers near you
📝 Tip: Don’t have your ID card handy? You can view a digital version under the ID Card section in JoinHealth.
What Is an In-Network Provider?
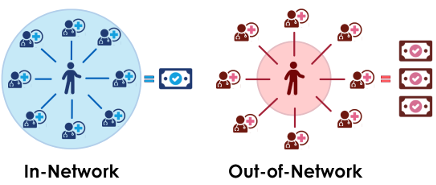
An in-network provider is a doctor, specialist, hospital, or healthcare facility that has an agreement with your health plan to accept negotiated payments for covered services. This helps reduce what you pay out of pocket.
In contrast, out-of-network providers do not have this agreement, so you may pay more when you visit them—and your health plan may cover less.
Why Choose In-Network Providers?
Using in-network providers can make a big difference in your healthcare experience:
✅ Higher Savings
In-network providers accept negotiated payments, which means you save money on your copayments, coinsurance, and deductible costs.
✅ More Plan Coverage
Your health plan typically covers more of the cost when you stay in network, so you pay less overall.
✅ Simpler Claims Process
In-network providers handle the claims paperwork for you, so you don’t have to submit claims or wait for reimbursement.
What Happens If You Use an Out-of-Network Provider?
You always have the choice to see an out-of-network doctor. However, it is very important to review your Summary Plan Description (SPD) to see what coverage, if any, you may have when seeing a doctor outside of your plan’s network.
- Some plans may not cover out-of-network providers. In that case, you will likely be responsible for the full cost if you choose to see an out-of-network doctor or specialist.
- Other plans may cover out-of-network providers, but you must pay a separate and higher deductible, copayment, and/or coinsurance.
- If you have out-of-network coverage, you may have to pay your provider up front and then submit the claim to your health plan.
Here’s an example where Paul does not have out-of-network benefits:
Paul Smith sees an out-of-network chiropractor and is charged $150 for one visit. He does not have out-of-network coverage. That means:
- He must pay the entire $150 out of pocket.
- His payments will not count towards his deductible or out-of-pocket maximum.
Here’s an example where Jane has out-of-network benefits:
Jane Smith sees an out-of-network chiropractor and is charged $150 for one visit. Her health plan’s maximum allowable benefit for this service is $100. That means:
- She must pay the entire $150 out of pocket
- She submits a claim to her health plan
- Only $100 counts toward her out-of-network deductible
Note: The “maximum allowable benefit” is the highest amount your health plan may pay for a service, based on usual rates in your area.
We’re Here to Help
Using in-network providers helps you get the most value from your plan. If you have questions about your provider network, you can:
- Contact our customer service team through the JoinHealth Contact Us section
- Call the customer service number listed on the back of your ID card.
Important Reminder
This article is for general educational purposes only and does not constitute medical, legal, financial, or benefits advice. Please consult your doctor if you have any questions related to your medical care or treatment. Actual benefits, coverage details, and out-of-pocket costs may vary by plan. Always refer to your Summary Plan Description (SPD) or contact your plan administrator for specific information about your coverage.